Why a Business Owner’s Policy is Essential for Your Business
A Business owners policy (BOP) is a bundled insurance package that combines general liability and commercial property coverage into one cost-effective policy, designed specifically for small and mid-sized businesses. Instead of buying separate policies for each risk, a BOP simplifies your insurance by protecting against the most common threats—like customer injuries, property damage, theft, and lost income from covered events—all in a single package.
Here’s what a Business Owner’s Policy typically includes:
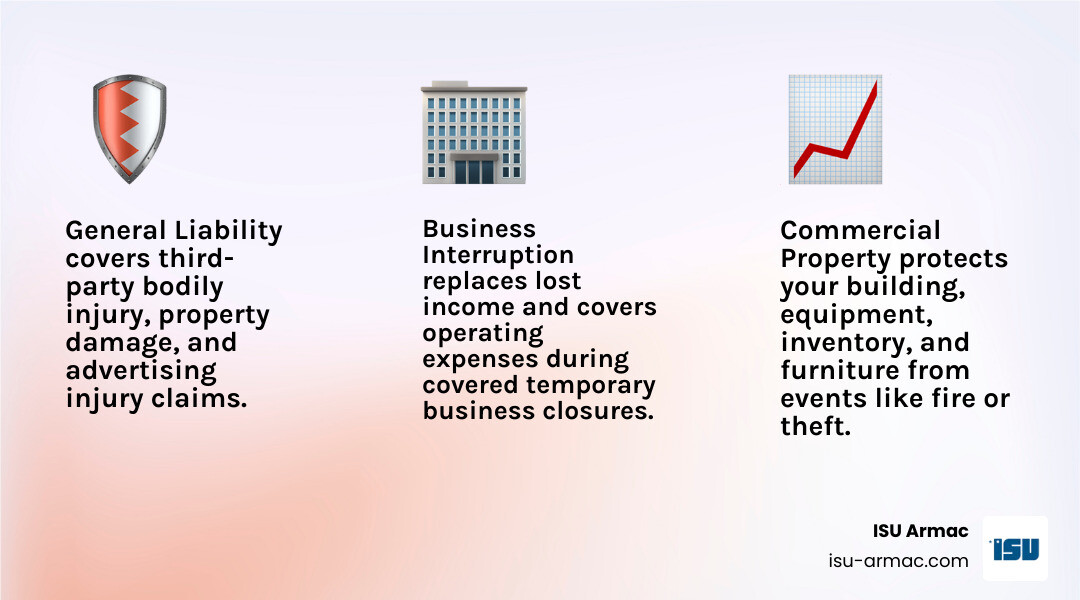
- General Liability Insurance – Covers third-party injuries, property damage, and advertising injury
- Commercial Property Insurance – Protects your building, equipment, inventory, and furniture from fire, theft, and vandalism
- Business Interruption Insurance – Replaces lost income and covers operating expenses if your business must temporarily close due to a covered event
Cost: BOPs can cost as little as $25 to $400 per month, depending on your industry, location, revenue, and coverage needs. On average, small businesses pay around $141 per month for a BOP.
Who qualifies: Generally, businesses with fewer than 100 employees and less than $5 million in annual revenue are eligible for a BOP, including retail stores, offices, small restaurants, contractors, and wholesalers.
In 2018, Canadian insurers paid out $6.5 billion in commercial property claims and $3.7 billion in commercial liability claims. These numbers highlight just how important it is to have the right protection in place. A BOP gives you that protection without the hassle of managing multiple policies or paying for coverage you don’t need.
I’m Ryan McEachron, Chief Executive Officer of ISU-ARMAC in Victorville, where I’ve been helping local business owners secure comprehensive and affordable Business owners policy coverage for years. In this guide, I’ll walk you through everything you need to know about BOPs—what they cover, what they cost, and how to customize one to fit your unique business needs.
Business owners policy terminology:
What is a Business Owner’s Policy (BOP)?

A Business owners policy (BOP) is a specialized insurance package that combines protection for major property and liability risks. It’s truly a game-changer for small to medium-sized businesses, offering a streamlined and cost-effective way to secure comprehensive coverage. Think of it as a convenient, all-in-one starter pack for business insurance, designed to handle the typical risks businesses like yours face every day in Southern California. We understand that as a business owner, your plate is already full. Our goal is to make insurance one less thing you have to worry about, allowing you to focus on what you do best: growing your business.
The Core Concept of a Business Owner’s Policy
The beauty of a Business owners policy lies in its simplicity and efficiency. Instead of juggling separate policies for general liability, property damage, and business interruptions, a BOP bundles these essential coverages into one neat package. This means you get:
- Bundled Coverage: Your core risks are covered under a single policy, eliminating gaps that might occur with fragmented insurance.
- Simplified Management: One policy means one premium, one renewal date, and one point of contact for most of your insurance needs. This saves you valuable time and reduces administrative headaches.
- Cost Efficiency: By bundling, insurers can often offer a lower premium than if you purchased each coverage individually. It’s like getting a discount for buying in bulk!
- Designed for Small Businesses: BOPs are specifically crafted to meet the unique needs and risk profiles of small to mid-sized businesses, providing robust protection without the complexity or expense of larger commercial packages.
As the Insurance Information Institute (III) explains, a Business owners policy is a combination of business property and liability protection specifically designed to meet the insurance needs of small and mid-size businesses. To learn more about the fundamental structure of these policies, you can explore Understanding business owners policies (BOPs).
Who is the Ideal Candidate for a BOP?
While incredibly versatile, a Business owners policy isn’t a one-size-fits-all solution for every business. It’s generally best suited for businesses with a physical location, moderate risk exposure, and a relatively straightforward operational structure. Typically, companies with 100 employees or fewer and revenues of up to about $5 million or less are candidates for a BOP.
Here are some types of businesses that often find a BOP to be the perfect fit:
- Retail Stores: From boutiques in Apple Valley to hardware stores in Victorville, businesses with physical premises and inventory are prime candidates.
- Office-Based Businesses: Accountants, consultants, real estate agencies, and other professional services operating from an office.
- Small Restaurants and Cafes: Protecting against slips, spills, and property damage in your cozy Hesperia eatery.
- Contractors: While not all contractor risks are covered, a BOP provides a solid foundation for general liability and property for tools and equipment.
- Wholesalers and Distributors: Businesses that store and distribute goods often benefit from the property and liability components.
- Service-Based Businesses: Hair salons, dry cleaners, and other service providers with a physical location.
Essentially, if your business has a physical location, interacts with customers or clients, and has assets that could be damaged or stolen, a Business owners policy is definitely worth considering. It’s about protecting your livelihood and ensuring continuity, even when unexpected events occur.
Core Coverages: What’s Included in a Standard BOP?
A standard Business owners policy typically bundles three critical types of insurance coverage, providing a strong foundation of protection against common incidents. Understanding these components helps clarify the value and breadth of the policy, giving you peace of mind that your business in Southern California is well-protected.
Commercial General Liability (CGL) Insurance
Often called “slip and fall” insurance, Commercial General Liability (CGL) is a cornerstone of any Business owners policy. It protects your business from financial loss resulting from claims of injury to others or damage to their property caused by your business operations, products, or services. This is crucial in today’s litigious society. Imagine a customer tripping over a loose rug in your Oak Hills shop, or an employee accidentally damaging a client’s valuable property during a service call. CGL has your back.
Specifically, CGL typically covers:
- Bodily Injury to Third Parties: This covers medical expenses, loss of income, and pain and suffering if someone (who isn’t an employee) is injured on your premises or due to your business operations. For example, if a client slips on a wet floor in your office.
- Damage to Others’ Property: If your business or employees accidentally cause damage to someone else’s property, CGL helps cover the repair or replacement costs.
- Advertising Injury (Libel or Slander): This covers claims arising from false arrest, malicious prosecution, wrongful eviction, and even copyright infringement in your advertising, such as mistakenly using another company’s logo.
- Legal Defense Costs: Even if a claim against your business is unfounded, legal battles can be expensive. CGL helps cover attorney fees and court costs, regardless of the outcome.
- Medical Payments: This can cover small medical expenses for minor injuries to third parties on your premises, often without determining fault, helping to prevent larger lawsuits.
Commercial Property Insurance
Your business relies on its physical assets, from the building itself to the inventory within it. Commercial Property Insurance, a vital part of a Business owners policy, protects these assets from a wide range of perils. It covers the repair or replacement of damaged or destroyed buildings, equipment, stock, furniture, or fixtures. This is especially important in Southern California, where businesses need to protect against various risks.
This coverage typically includes:
- Owned or Rented Buildings: Whether you own your storefront in Victorville or lease office space in Apple Valley, this covers damage to the structure itself.
- Business Equipment and Tools: Your computers, machinery, specialized tools, and other essential equipment are covered against damage or theft.
- Office Furniture: Desks, chairs, filing cabinets – the items that make your workspace functional.
- Inventory and Stock: The products you sell or the materials you use for your services are protected.
- Protection from Fire, Theft, and Wind: These are common perils that can wreak havoc on a business. Imagine a fire damaging your restaurant in Hesperia; this coverage helps rebuild.
While general liability insurance protects against losses to others’ property, property insurance within a BOP specifically protects your own business property. We’ve seen how devastating property damage can be, and this coverage is designed to help you get back on your feet quickly.
Business Interruption Insurance
What happens if a covered event, like a fire or severe storm, forces your business to close its doors temporarily? While Commercial Property Insurance covers the physical damage, you’d still be losing income and facing ongoing expenses. That’s where Business Interruption Insurance, often called Business Income Coverage, steps in. It’s a critical component of a Business owners policy that protects your income stream when you can’t operate. BOPs usually also include business interruption insurance to help cover lost income due to a covered event like a fire until you get your business back on its feet.
This coverage typically includes:
- Lost Income During Closure: Replaces the profits you would have earned had the disaster not occurred.
- Ongoing Operating Expenses (Rent, Payroll): Helps you continue to pay essential bills like rent, utility costs, and even employee salaries, so you don’t lose your team during downtime.
- Extra Costs of a Temporary Location: If you need to move to a temporary spot to continue operations, this can cover the additional rent or setup costs.
- Covered Perils like Fire or Disaster: Protection kicks in when the interruption is due to a covered event, allowing your business to recover financially.
Without business interruption coverage, many small businesses struggle to survive a temporary shutdown. It’s not just about rebuilding your physical space; it’s about preserving your financial stability.
Key Benefits and Cost of a Business Owner’s Policy
One of the primary reasons business owners choose a Business owners policy is for its combination of comprehensive coverage and affordability. It addresses multiple risks without the complexity and higher cost of individual policies. We believe that protecting your business shouldn’t be a financial burden, and a BOP is often the smartest way to achieve that.

Why a BOP is a Smart, Cost-Effective Choice
A Business owners policy is more than just a convenience; it’s a strategic financial decision for many small businesses. It offers significant advantages over purchasing separate policies:
- Bundling Discount: Insurers reward you for combining multiple coverages. This means you typically pay less for a BOP than you would for individual general liability, commercial property, and business interruption policies bought separately. It’s a simple way to save money without compromising on protection.
- Lower Premiums Than Separate Policies: As mentioned, the combined premium for a BOP is generally more affordable. This makes comprehensive insurance accessible for businesses that might otherwise struggle to afford robust protection.
- Broad Protection from Common Risks: A BOP is designed to cover the most frequent and significant risks faced by small businesses. This means you get essential coverage without paying for highly specialized policies you may not need.
- Simplified Insurance Management: With one policy, one bill, and one renewal date, managing your insurance becomes much easier. This frees up your time to focus on running your business, rather than sifting through multiple insurance documents.
A Business owners policy combines coverage for all major property and liability insurance risks as well as many additional coverages into one package policy suitable for most small businesses. It’s truly a smarter and more convenient choice for business owners looking for robust protection.
How Much Does a BOP Typically Cost?
The cost of a Business owners policy can vary widely, but it’s often more affordable than many business owners expect. While the average annual cost our customers paid for a BOP was $1,687, or about $141 a month, every small business is unique.
Here’s a breakdown of factors that influence the price:
- Industry Risk: Some industries are inherently riskier than others. A low-risk consulting firm, for example, will likely pay less than a small restaurant or a contractor. BOP insurance coverage can cost as little as $25/month for some low-risk businesses.
- Location: Your business’s physical location, especially in Southern California, can impact costs due to factors like local crime rates, weather patterns, and proximity to fire services.
- Revenue: Generally, businesses with higher revenues may require higher coverage limits, which can increase premiums.
- Claims History: A history of frequent or large claims will typically lead to higher insurance costs.
- Coverage Limits and Deductibles: Choosing higher coverage limits will increase your premium, while opting for a higher deductible can lower it.
- Property Value: The value of your building, equipment, and inventory directly affects the cost of the property insurance component.
- Number of Employees: More employees can sometimes lead to slightly higher liability risks, influencing the premium.
A Business owner’s policy can cost as little as $35 per month or as much as $400 per month. The best way to find out how much a BOP insurance will cost for your business is to get a personalized quote from us. We’ll shop multiple carriers to find the best rates for your specific needs in Apple Valley, Victorville, Hesperia, or Oak Hills.
BOP Eligibility and Common Exclusions
While a Business owners policy is an excellent option for many, it’s not available to every business. Insurers have specific criteria to determine eligibility, and the policy has standard exclusions that business owners should be aware of. Understanding these aspects helps ensure you choose the right coverage and avoid any surprises down the line.
What Types of Businesses Are Eligible for a Business Owner’s Policy?
Eligibility for a Business owners policy is primarily based on the size and risk profile of your business. Insurers typically look for businesses that present moderate risk and have relatively straightforward insurance needs. Generally, your business must have fewer than 100 employees, and less than $5 million in annual revenue to be eligible for a BOP.
Other common eligibility requirements include:
- Small Physical Premises: Businesses operating from a small office, storefront, or workshop.
- Low-Risk Industry: Industries like retail, professional services, and certain types of contracting are often eligible. Higher-risk businesses, such as manufacturing companies, car dealerships, bars, and auto repair shops, are typically excluded from BOP eligibility due to their increased exposure to unique or severe risks.
- Need for Less Than 12 Months of Business Interruption Insurance: If your business would require a very long period of business interruption coverage (e.g., more than 12 months), a BOP might not be the right fit.
To get a clearer picture of whether your business qualifies, it’s always best to consult with an insurance professional. We can help assess your specific situation and guide you toward the best insurance solution.
What Isn’t Covered? Common BOP Exclusions
Even with its broad coverage, a Business owners policy doesn’t cover every possible risk your business might face. These exclusions are standard across the industry and highlight the need for additional, specialized policies if your business requires them. It’s crucial to understand these limitations to avoid coverage gaps.
Common BOP exclusions include:
- Professional Liability (Errors & Omissions): This is a significant exclusion. A BOP will cover general liability, but it won’t protect you if a client sues you for mistakes in your professional advice or services. For example, if a consultant gives bad advice that causes a client financial harm, a BOP won’t cover it. Professional services require a separate professional liability (E&O) policy.
- Workers’ Compensation: Injuries to your employees that occur on the job are not covered by a BOP. This requires a separate Workers’ Compensation policy, which is mandatory in nearly all states, including California, for businesses with employees.
- Commercial Auto Insurance: Accidents involving business vehicles (whether owned, leased, or even personal vehicles used for business) are not covered by a BOP. You’ll need a separate commercial auto policy.
- Employee Health and Disability: These benefits for your employees are not part of a BOP and require separate insurance plans.
- Flood and Earthquake Damage: In Southern California, this is a particularly important exclusion. Most property insurance policies, including those in a BOP, do not cover natural disasters like earthquakes and floods. You would need to purchase separate flood insurance (often through the National Flood Insurance Program) and earthquake insurance to protect against these specific perils.
- Normal Wear and Tear: Damages that occur gradually over time due to normal use are not covered.
- Intentional Acts: A BOP will not cover damages or injuries that result from intentional misconduct by you or your employees.
- Data Breaches: While some BOPs might have limited cyber coverage, comprehensive protection against cyberattacks and data breaches usually requires a separate cyber liability insurance policy.
Knowing what your Business owners policy doesn’t cover is just as important as knowing what it does cover. This allows us to work with you to identify any potential gaps and recommend additional policies to ensure your business is fully protected.
Customizing Your BOP with Optional Coverages
A standard Business owners policy covers the most common risks, but your business is unique. We understand that a one-size-fits-all approach doesn’t work for every business in Southern California. That’s why you can improve your protection by adding optional coverages, also known as endorsements or riders, to tailor the policy to your specific needs. This customization allows you to create a truly comprehensive insurance solution that fits your exact operational requirements.
Popular Endorsements to Improve Your Business Owner’s Policy
These additional coverages can be crucial for addressing specific risks that aren’t typically included in a basic Business owners policy:
- Cyber Liability Insurance: With 60% of businesses that fell victim to cybercrime last year being small- and medium-sized businesses, cyber liability is no longer optional. This coverage helps protect your business from the financial fallout of data breaches, hacker attacks, and other cyber incidents. It can cover costs for forensic investigation, data restoration, legal defense, and notifying affected customers.
- Data Breach Coverage: Often included within or closely related to cyber liability, this specifically addresses the costs associated with a breach of sensitive customer or employee data.
- Hired and Non-Owned Auto Liability: If your employees use their personal vehicles for business errands, or if you rent vehicles for business purposes, this endorsement extends liability coverage to those situations, protecting your business from claims arising from accidents.
- Equipment Breakdown: This covers damage to essential machinery and equipment (like HVAC systems, refrigerators, or production equipment) due to mechanical or electrical breakdown, which is typically excluded from standard property coverage.
- Spoilage Coverage for Perishable Goods: If your business deals with food, flowers, or other perishable items, this covers losses due to power outages or equipment breakdown that causes your inventory to spoil.
- Commercial Crime Insurance: Protects against losses from theft, forgery, embezzlement, and other fraudulent acts committed by employees or third parties.
- Professional Liability (Errors & Omissions): As mentioned earlier, while typically excluded from a standard BOP, this is a critical add-on for service-based businesses in fields like consulting, IT, real estate, or marketing, protecting against claims of negligence or mistakes in your professional services.
By carefully selecting these endorsements, we can help fine-tune your Business owners policy to address the specific vulnerabilities of your business, providing robust protection that leaves no critical stone unturned. For more detailed information on how we can customize your business insurance, visit our More info about business insurance services page.
Frequently Asked Questions about Business Owner’s Policies
We often get excellent questions from business owners in Apple Valley, Victorville, and across Southern California about Business owners policies. Here are some of the most common ones we hear, along with our answers:
What is the difference between a BOP and a Commercial Package Policy (CPP)?
This is a great question! Think of it this way:
- Business Owners Policy (BOP): This is like a pre-packaged meal deal. It bundles essential coverages (general liability, property, business interruption) into one policy, usually at a lower premium. It’s designed for small to mid-sized businesses with relatively low risks and straightforward needs. It’s efficient and cost-effective for businesses that fit the mold.
- Commercial Package Policy (CPP): This is more like ordering à la carte. It allows larger or more complex businesses to pick and choose specific coverages and limits to create a highly customized policy. CPPs are for businesses that don’t fit the standard BOP criteria due to their size, industry, or unique risk exposures, offering much greater flexibility but often at a higher cost.
For most small businesses we work with in Southern California, a BOP is the ideal solution due to its comprehensive nature and affordability.
Does a BOP cover employee injuries?
No, a Business owners policy does not cover employee injuries. Injuries to employees that occur on the job are covered by a separate Workers’ Compensation policy. In California, Workers’ Compensation insurance is generally required by law for businesses with employees, regardless of whether they are full-time or part-time. It provides medical benefits and wage replacement for employees who are injured or become ill as a direct result of their work.
Can I get a BOP if I work from home?
Absolutely! A Business owners policy is often ideal for home-based businesses, especially if you have clients visiting your home, store business inventory, or use valuable equipment. A standard home insurance policy typically offers very limited, if any, coverage for business-related liability or property. A BOP for a home-based business provides the crucial liability protection against customer injuries on your property and covers your business equipment and inventory, offering protection that your homeowners policy simply can’t. It’s a smart way to ensure your home-based venture is properly safeguarded.
Conclusion: Securing the Right Protection for Your Business
A Business owners policy (BOP) offers a smart, affordable, and comprehensive way for small business owners in Southern California to protect what they’ve built. By bundling general liability, commercial property, and business interruption insurance, a BOP addresses the most critical risks in a single, manageable policy. It simplifies your insurance, saves you money compared to buying separate policies, and provides the peace of mind you need to focus on running and growing your business.
We know that navigating business insurance can feel overwhelming, but you don’t have to do it alone. At ISU-ARMAC, we are dedicated to helping business owners in Apple Valley, Victorville, Hesperia, and Oak Hills find the perfect insurance solution. Our expertise lies in shopping multiple top-rated carriers to find a policy that fits your business and your budget perfectly. We’ll help you understand your options, customize your BOP with essential endorsements, and ensure you have the right coverages for your specific operation.
Don’t leave your business vulnerable to unexpected risks. Let us help you secure the protection you deserve.